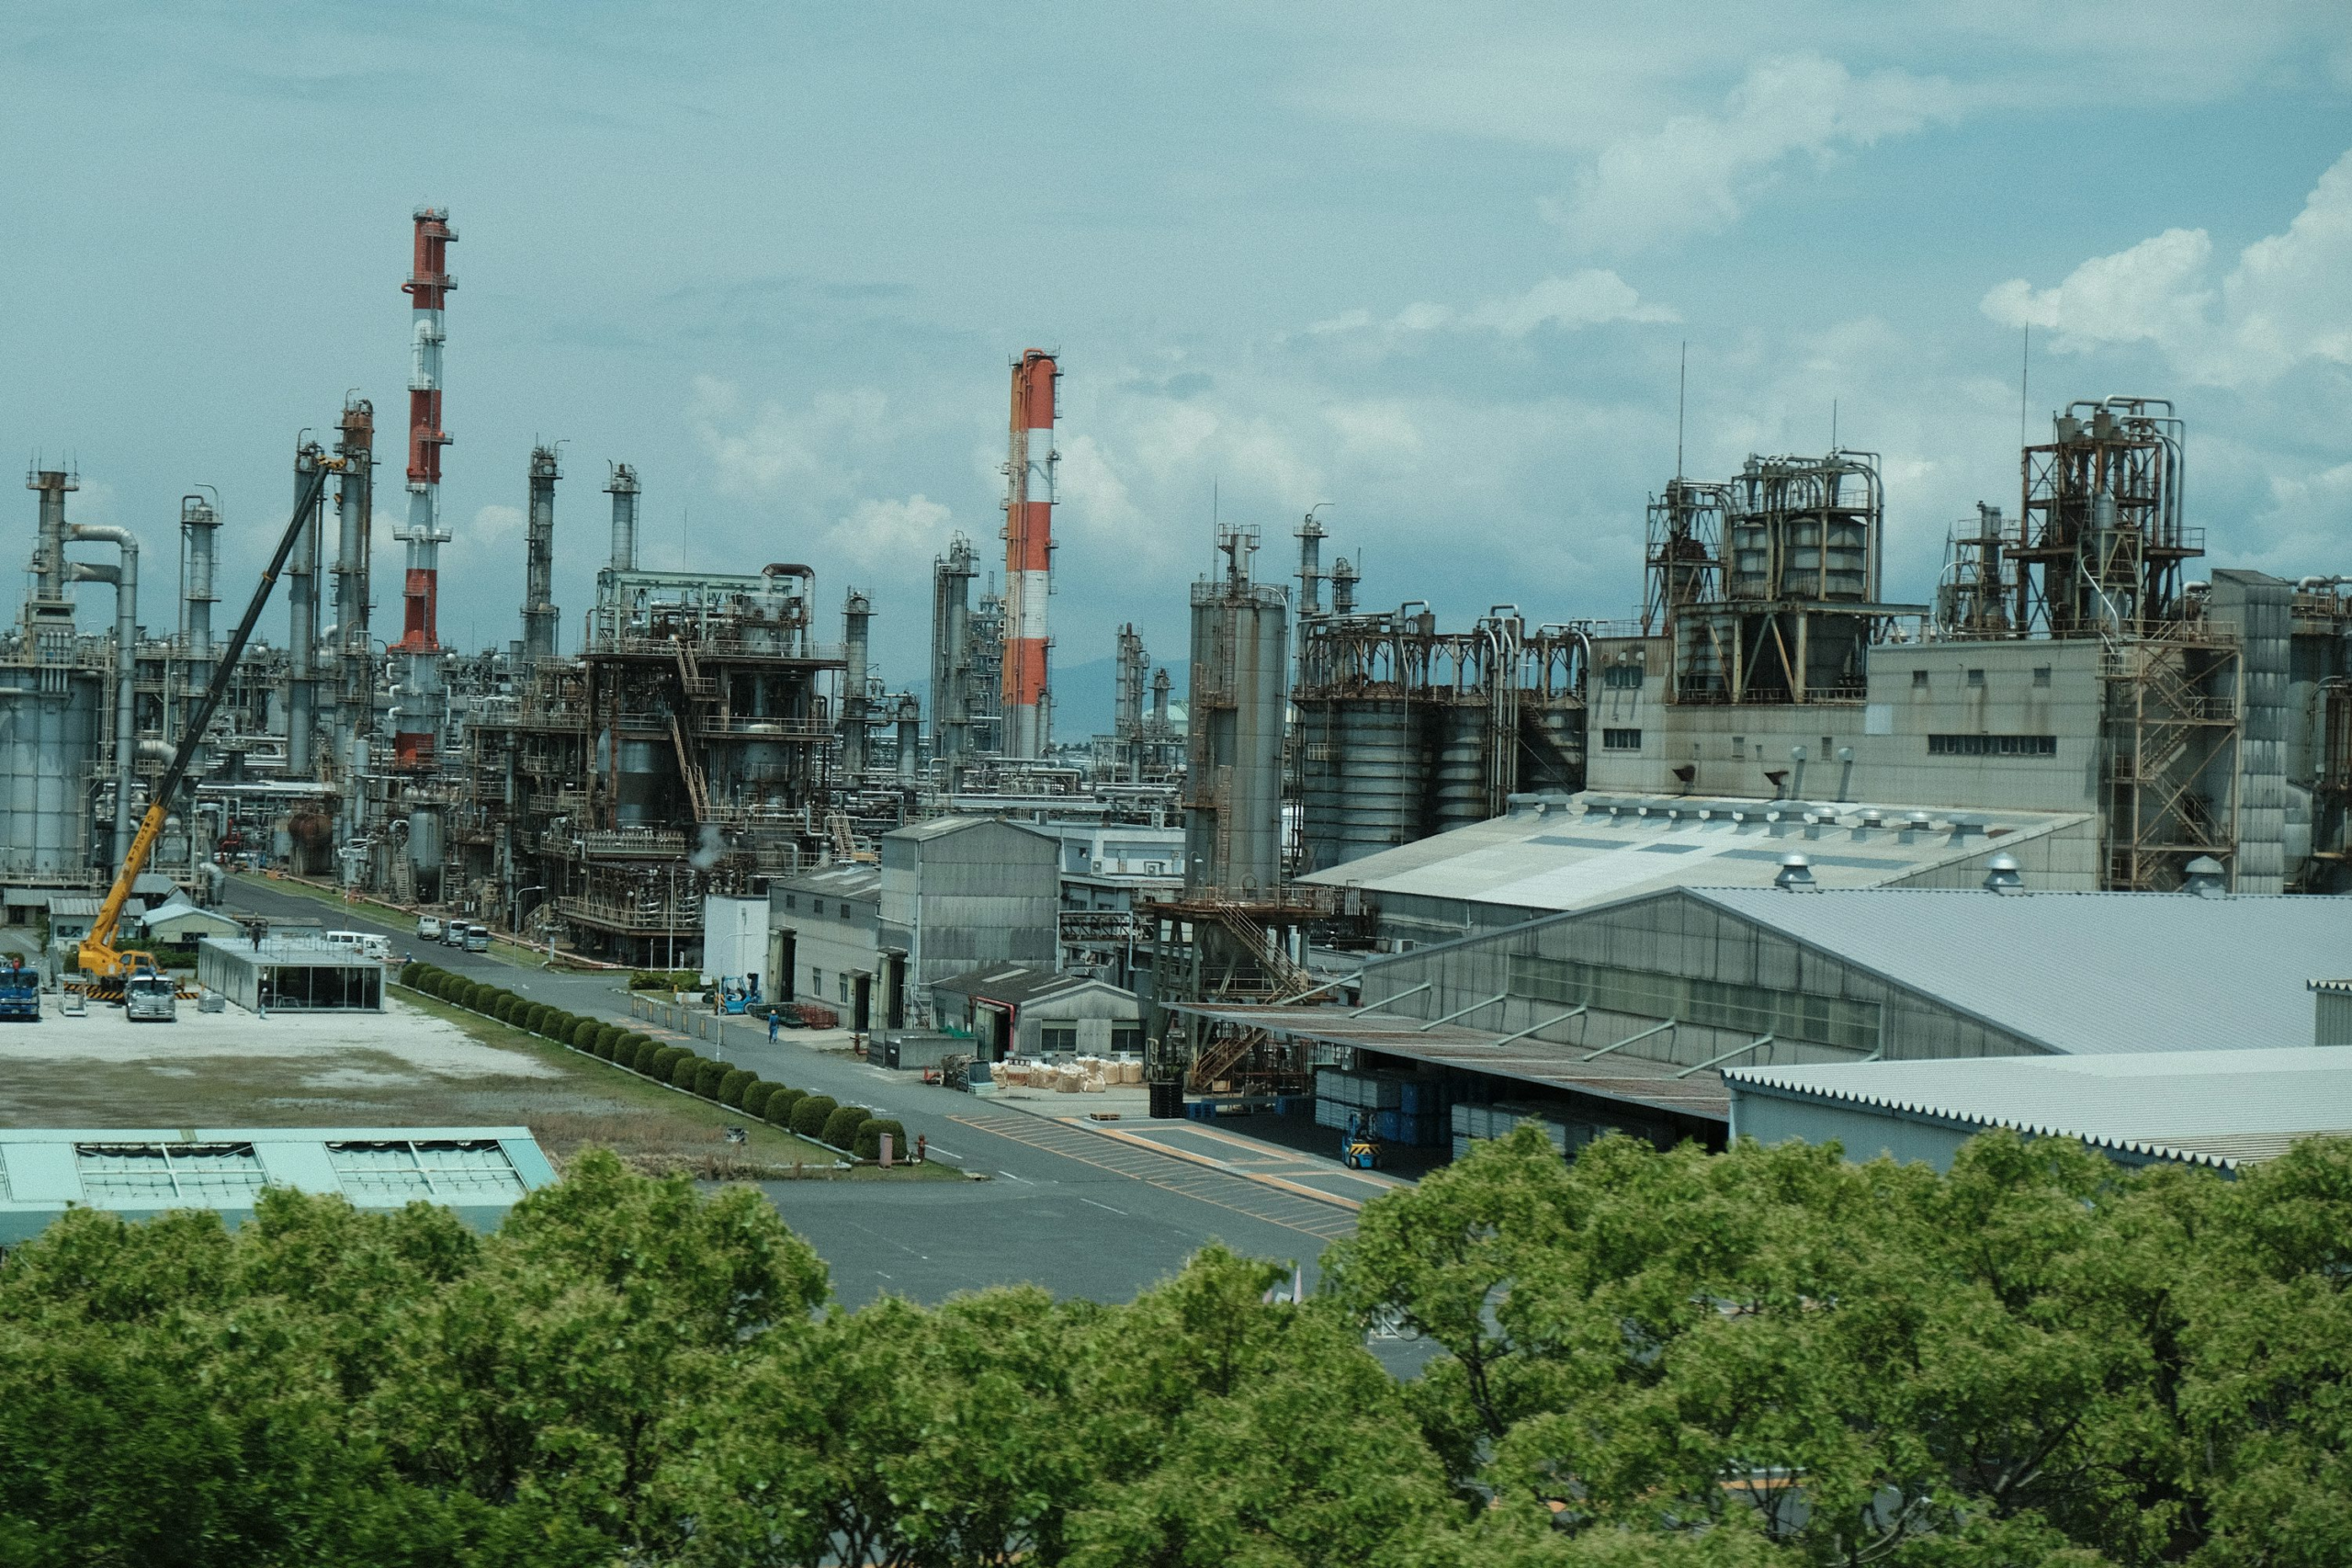
European Semiconductor Manufacturing Company has reached the topping-out stage at its new semiconductor factory in Dresden, completing the main building shell a little over two years after construction began.
The €10 billion project is a joint venture led by Taiwan Semiconductor Manufacturing Company, which holds a 70% stake, with Bosch, Infineon Technologies, and NXP Semiconductors each owning 10%. The factory is intended to supply automotive and industrial semiconductor customers from a new European 300mm wafer-production base.
More than 2,000 construction workers have been involved in assembling roughly 30,000 prefabricated concrete elements at the Dresden site. Around 600 companies have participated in the wider project, reflecting the breadth of civil engineering, utilities, cleanroom, electrical, and specialist construction work required before semiconductor-production equipment can be brought into a fab.
The completed factory is planned to operate TSMC process technology spanning 28/22-nanometre planar CMOS and 16/12-nanometre FinFET. When fully operational, the original project specification calls for monthly capacity of around 40,000 300mm wafers.
Those process nodes matter because automotive and industrial electronics have rather different requirements from the leading-edge processors used in smartphones and artificial-intelligence accelerators. Vehicle controllers, industrial processors, connectivity devices, mixed-signal components, and embedded systems often depend on mature or specialty manufacturing technologies where reliability, qualification, and long-term availability outweigh the benefits of pushing transistor geometry to the smallest available node.
The supply shortages experienced earlier in the decade underlined that distinction. Vehicle factories were disrupted by shortages of relatively conventional controllers and other components because a low-cost semiconductor can still stop a high-value production line when there is no qualified alternative available.
ESMC is intended to put more of that manufacturing capacity close to European customers. The project sits within the European Chips Act framework and has received €5 billion of German state support, illustrating the scale of public intervention considered necessary to attract semiconductor fabrication investment into Europe.
The economics explain some of that support. Wafer fabs require large capital expenditure before the first commercial wafer is produced, followed by substantial recurring costs for electricity, ultrapure water, process gases, chemicals, specialist maintenance, contamination control, and highly skilled labour.
Once production equipment begins operating, yield becomes as important as nominal capacity. A facility capable of processing 40,000 wafers a month creates useful industrial output only if successive process stages reproduce structures within tight tolerances and a commercially acceptable proportion of finished dies pass electrical testing.
Dresden provides a stronger starting point than most European locations because the surrounding semiconductor ecosystem is already substantial. Infineon, GlobalFoundries, and Bosch have major manufacturing operations in the region, while the Silicon Saxony cluster encompasses thousands of companies and more than 80,000 employees across microelectronics, software, suppliers, research, and engineering services.
That density reduces one of the less visible constraints on new semiconductor capacity: people. Process engineers, facilities specialists, equipment technicians, contamination-control experts, automation engineers, and yield specialists cannot be created simply by commissioning another building. ESMC has already been preparing future employees for the operating culture and technical demands of the new plant.
The factory will also draw on a wider European supply base. Semiconductor manufacturing requires pumps, valves, vacuum equipment, filtration, chemicals, gases, metrology, material handling, automation, cleanroom components, maintenance services, and highly specialised machinery from suppliers spread across several countries.
For Bosch, Infineon, and NXP, participation gives each company a strategic interest in a foundry intended specifically for markets where they already have sizeable customer positions. It does not make Europe self-sufficient in semiconductor production, nor would rebuilding every part of the global supply chain within one region be economically realistic, but it creates another qualified source for components central to European vehicle and industrial production.
The topping-out ceremony therefore closes the most visible phase of the project rather than the difficult one. A semiconductor fab becomes useful only after utilities are commissioned, production tools are installed and qualified, process recipes are transferred, staff are trained, customers qualify parts, and yield rises sufficiently for dependable commercial output.
Dresden now has the building in which that work can happen. The next measure of progress will be less architectural: whether ESMC can turn €10 billion of construction, equipment, engineering, and public support into stable wafer output on the timetable its automotive and industrial customers are expecting.