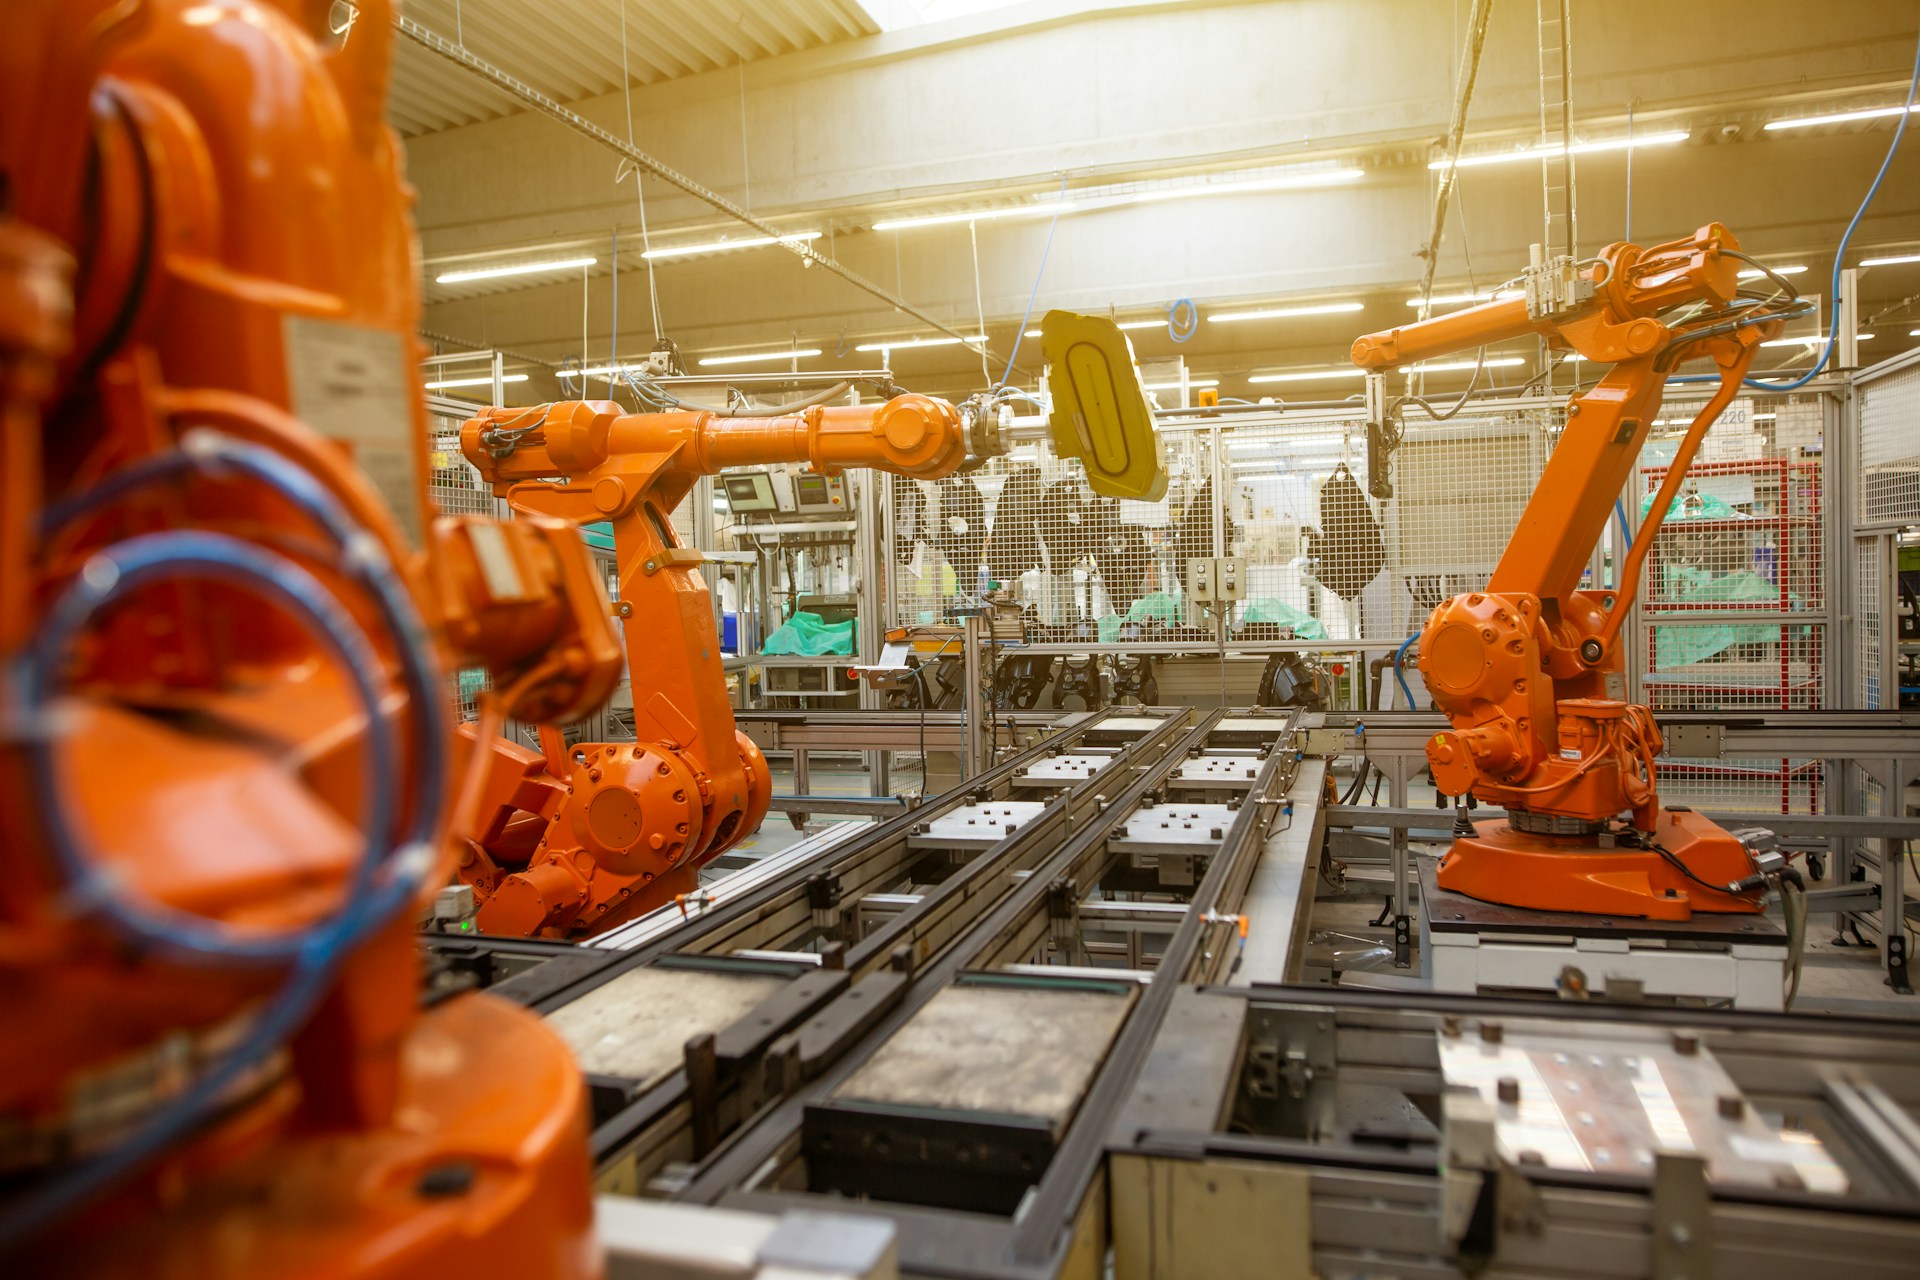
The International Federation of Robotics says the global operational stock of industrial robots reached 5.079 million units in 2025, an increase of 9% in a year. Factories installed 603,000 new robots during the period, pushing annual deployments up 11% and extending the long-term expansion of automation across manufacturing.
The headline number conceals an increasingly uneven regional market. China accounted for 59% of global installations after deploying 354,000 industrial robots during 2025, an increase of 20% from the previous year. Chinese robot manufacturers supplied 195,000 of those installations, giving domestic vendors a 55% share of their home market.
The United States moved ahead of Japan to become the world’s second-largest industrial robot market, with installations rising 12% to almost 38,500 units. Japan recorded 36,219 installations, down 19%, while South Korea installed around 30,000 units, a decline of 1%. India remained smaller in absolute terms but continued to expand rapidly, installing almost 10,500 robots, up 15%.
Europe was weaker. Germany remained the largest European market and accounted for 41% of installations across the European Union, but annual sales fell 8% to 24,842 units. Italy installed about 7,800 robots, down 11%, while France recorded almost 4,500, a decline of 8%. Spain installed roughly 4,300 units, 15% fewer than in 2024.
Those differences matter because installation data provides a partial indication of where manufacturers are committing capital to new production capacity and process automation. It is not a direct productivity ranking: factories differ considerably in sector, product mix and labour intensity, while one robot in an automotive body shop is not equivalent to a machine handling lower volume production elsewhere. The direction of investment is nevertheless difficult to ignore.
China’s scale increasingly shapes the competitive environment for automation suppliers. A market absorbing more than half of all new industrial robots gives manufacturers and integrators substantial volume over which to develop products, expand service networks and reduce unit costs. Domestic Chinese suppliers taking the majority share adds another layer because established international robot manufacturers face stronger local competition in the world’s largest automation market.
The US increase reflects a different industrial pattern. Manufacturing investment, labour availability and moves to increase domestic production are expanding the range of applications in which automation can be justified. IFR expects supply resilience and changes in industrial and trade policy to support further relocation of production into higher wage economies, where labour costs can strengthen the business case for automated processes.
Automation does not follow a simple relationship with wages. Integration cost, cycle time, production volume, product stability, safety and the availability of engineering support all affect whether a robot cell is commercially useful. Smaller manufacturers can struggle to justify conventional automation when batches change frequently or programming and fixture work consumes too much of the potential saving.
Technology is changing some of those constraints. Machine vision and sensing allow robots to work with less tightly controlled part presentation, while advances in artificial intelligence are widening the range of perception and decision tasks that can be handled automatically. Easier programming and system integration can also reduce engineering effort, which matters for manufacturers that do not employ large internal automation teams.
The 5.079 million robot installed base should therefore be read as accumulated production infrastructure rather than a count of experimental technologies. Industrial robots deployed in welding, assembly, machine tending, palletising, coating and materials handling are capital assets expected to operate for years. Growth in the operational stock means more factories are building automated equipment into normal production rather than treating robotics as an isolated improvement project.
IFR also recorded growth across the three largest customer industries. Robot installations in electronics and automotive each increased by 10% during 2025, while the metal and machinery sector rose by 22%. Collaborative robot installations reached 66,000 units, equal to 11% of the overall market, although their 7% growth rate was slower than industrial robotics as a whole.
The outlook suggests that expansion will continue. IFR forecasts global installations to increase another 9% to around 655,000 units in 2026 before reaching approximately 806,000 units in 2029. If achieved, that would add several million further installations over the next few years while the existing fleet continues to age, creating parallel demand for new systems, replacement equipment, software and maintenance.
The geographical balance may prove more consequential than the global total. Europe still contains major robot manufacturers and highly automated industries, but its largest markets contracted during 2025 while China and the US expanded. Robot adoption alone will not determine industrial competitiveness, yet factories investing in automation accumulate process knowledge, integration skills and production data alongside the hardware itself.
Five million operating robots is therefore less a finishing line than evidence that automation has become ordinary manufacturing infrastructure at global scale. The next question is whether the regional investment gap widens as annual installations approach 800,000 units, or whether easier deployment and more capable systems allow slower markets to recover momentum.