Volkswagen Group, PowerCo, and Gotion High-tech have agreed to establish three joint ventures spanning lithium iron phosphate battery cells and cathode material production in Spain, Slovakia, and Morocco.
The arrangement expands a partnership running since 2020 from cell supply and technology cooperation into shared industrial production. It will cover PowerCo’s Valencia gigafactory, Gotion’s Šurany factory in Slovakia, and a new cathode material facility at Kenitra in Morocco, alongside joint procurement and sales activities in Europe.
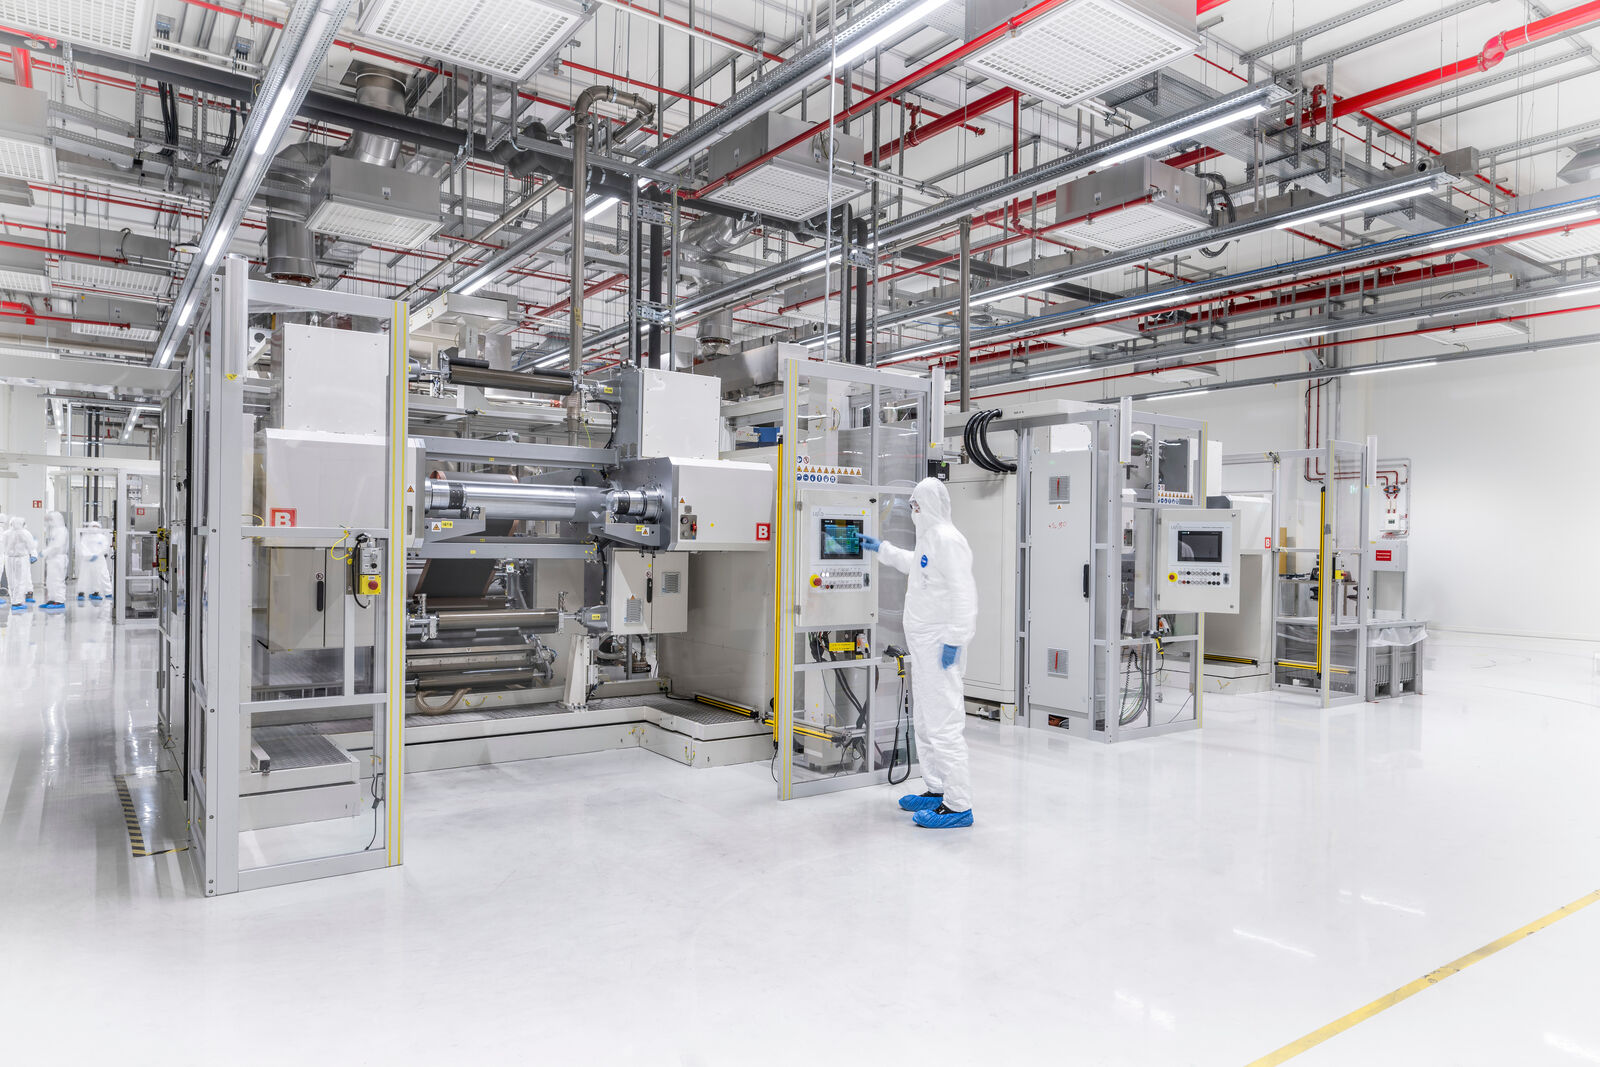
Valencia is intended to become the principal European LFP production hub within the structure. The PowerCo gigafactory now under construction is expected to transfer into a joint venture in which PowerCo retains a 51% majority interest and Gotion takes 49%. The partners plan to use the site for Unified Cells based on LFP chemistry, while previously announced investment and employment plans remain in place.
The ownership position is reversed at Šurany. Gotion will retain 51% of the joint venture around its Slovakian cell factory, with PowerCo holding 49%. Production is intended to serve electric vehicles and stationary energy storage, broadening the potential customer base beyond Volkswagen’s passenger car programmes.
Kenitra addresses another point in the manufacturing chain. A new facility there will produce cathode active material for LFP batteries, with Gotion again holding the 51% majority interest. PowerCo and Gotion say the plant is intended to diversify cathode material sourcing and provide a more regional supply route into European cell production.
The financial commitments reflect the assets being contributed. PowerCo expects to invest around €470 million by 2030 for its 49% interests in Šurany and Kenitra, while Gotion is expected to invest approximately €1.1 billion for its 49% share of the Valencia operation. The transactions remain subject to regulatory approvals and other closing conditions.
The agreement places lithium iron phosphate more firmly inside Volkswagen’s European battery strategy. LFP cells generally offer lower material costs, long cycle life, and strong thermal stability while avoiding nickel and cobalt in the cathode. Their lower energy density compared with some nickel rich chemistries can be a disadvantage where maximum range or minimum battery mass dominates the vehicle specification, but the economics are attractive for higher-volume vehicles and stationary storage.
Volkswagen expects European LFP demand to grow sharply through the remainder of the decade. The group says the chemistry currently represents roughly 10% of the regional market and could rise to between 40% and 60% by 2030. That range remains a forecast rather than a committed market outcome, with vehicle mix, commodity prices, pack engineering, charging performance, and competing chemistries all capable of changing adoption rates.
The cathode material element is as important as the headline cell factories. Cell assembly cannot create regional supply resilience if active materials remain concentrated elsewhere. Building cathode processing alongside cell capacity reduces one part of that exposure, although lithium extraction, refining, separator materials, electrolytes, graphite, equipment, and other inputs will continue to span several countries.
European LFP industrialisation is already moving beyond pilot scale. IBU-tec is developing a 15,000-tonne annual cathode material plant in Germany under a long term PowerCo agreement, with production expected from 2028. The Gotion partnership adds cell manufacturing and another cathode route around that emerging network.
Volkswagen is also adjusting its financial relationship with Gotion. Through Volkswagen China Investment, the group has agreed to sell a 5.3% equity stake in the Chinese battery company while retaining a significant strategic holding, board representation, and associated nomination rights. The share sale is separate from the manufacturing joint ventures and remains subject to regulatory clearance.
The industrial challenge now shifts to execution across three jurisdictions. Valencia and Šurany have to progress from construction and corporate restructuring into qualified LFP production, while Kenitra requires a new cathode material operation. Equipment installation, process qualification, supplier localisation, workforce training, product consistency, and vehicle validation will determine how quickly the partnership becomes a functioning production network.
Coordinating the three sites will also require material flows to be matched with cell output and customer demand. Cathode capacity that ramps too slowly can constrain cell plants, while excess material or cell capacity adds working capital and storage costs. Procurement and sales activity within the joint venture structure is intended to give the partners more control over that balance as European LFP volumes increase.
Regulatory approval is the immediate formal milestone, but construction and qualification will determine the industrial timetable. Ownership agreements create the framework; the more important test is whether Valencia, Šurany, and Kenitra can reach stable production at the quality, cost, and volume required for large-scale vehicle and energy storage programmes.